 Family office in Zurich
Overview
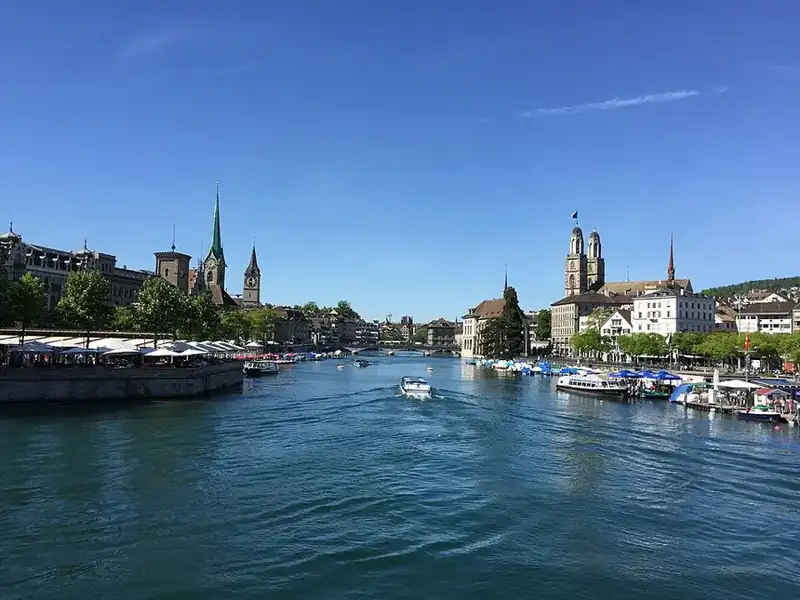
Zurich concentrates Switzerland's largest banks, many private and foreign banks, the SIX Swiss Exchange, insurers, reinsurers, independent asset managers, law firms and audit firms within a compact city with an international airport. For a family that runs its wealth actively — direct investments, private equity and real estate, bankable portfolios spread over several custodians — this ecosystem is the main reason to choose Zurich over smaller cantons. The trade-off is tax: Zurich has no special family office regime and its ordinary company and personal taxes are higher than in Zug or Schwyz. Many families therefore separate the questions of where the office operates and where the principals live.
Switzerland does not regulate the label 'family office'; it regulates functions. Under FinIA Article 2(2)(a), persons who manage solely assets of persons with whom they have business or family ties are outside the Act. FinIO Article 4 lists those ties: relatives in the direct line, collateral relatives up to the fourth degree, spouses and registered partners (and their relatives), coheirs, and portfolio managers controlled by such persons or by a trust or foundation set up for them — even if charitable entities are also beneficiaries. A single family office (SFO) built within these limits needs no FINMA licence. Professional trustees are treated in the same way: a private trust company serving only family trusts can stay outside the trustee licence.
Once an office manages assets for unrelated families on a commercial basis, it becomes a portfolio manager (or, for trusts, a trustee) under FinIA. Commerciality is presumed under FinIO Article 19 where gross earnings exceed CHF 50,000 a year, there are more than 20 contractual partners, or there is unlimited power of disposal over third-party assets above CHF 5 million; family-tie relationships are disregarded in the count. A licensed manager needs Swiss domicile and effective management, qualified managers of good repute, minimum capital of CHF 100,000, risk management and compliance, ongoing supervision by a FINMA-authorised supervisory organisation and an annual audit. Managing collective investment schemes above the FinIA Article 24 de minimis thresholds requires a manager of collective assets licence. An office that only advises clients other than the family must also consider FinSA conduct rules and, for client advisers of non-supervised firms, registration in a client adviser register.
Anti-money laundering is a separate analysis. A family office with powers of disposal over others' assets may qualify as a financial intermediary under AMLA unless an exemption for family or group relationships applies; where caught and not supervised by FINMA, it must join a recognised SRO and apply KYC, beneficial owner identification, record keeping and suspicious activity reporting. The new Legal Entities Transparency Act entered into force on 1 October 2026 and requires Swiss companies to report their beneficial owners to a federal register maintained by the Federal Office of Justice, with transitional deadlines for existing entities. Switzerland applies the CRS and FATCA, so each entity, trust and foundation in the structure must be classified and, where relevant, report.
Taxes shape the design. Canton Zurich abolished lump-sum (expenditure-based) taxation after a popular vote on 8 February 2009, effective 1 January 2010, so a principal living in Zurich is taxed on worldwide income and wealth at ordinary rates; families wanting the lump-sum regime typically live in a canton that still offers it (for example Zug, Schwyz or Geneva) and work in Zurich. Zurich voters rejected a reduction of the cantonal profit tax rate on 18 May 2025, leaving a combined effective company rate of roughly 19.5–19.6% in the city of Zurich, though participation relief largely removes tax on qualifying dividends and capital gains of a holding company. Zurich exempts spouses and direct descendants from cantonal inheritance and gift tax, and Swiss voters rejected a federal inheritance tax initiative on 30 November 2025. Switzerland has no domestic trust law but recognises foreign trusts under the Hague Trusts Convention, which is why Zurich offices often serve a common-law trust, a private trust company or a Liechtenstein foundation.
Key benefits
- Statutory exemption from FinIA licensing for a single family office serving persons with family ties
- Direct access to Switzerland's largest concentration of private banks, custodians, asset managers and the SIX Swiss Exchange
- Deep pool of investment, legal, tax and audit professionals in English and German
- Participation relief for holding income and the option of a Swiss limited qualified investor fund (L-QIF) for pooled family investments
- Spouses and direct descendants exempt from Zurich inheritance and gift tax
- Recognition of foreign trusts under the Hague Convention and easy combination with Liechtenstein foundations
- A clear upgrade path to a FINMA-licensed multi-family office if other families are admitted
- Political, legal and currency stability with an extensive double tax treaty network
Requirements
- SFO exemption: serve only persons with family ties under FinIO Art. 4 (direct line, collateral relatives to the fourth degree, spouses and registered partners, coheirs, or entities, trusts and foundations controlled by or set up for the family)
- MFO: FINMA licence as portfolio manager or trustee where the office acts commercially for third parties (FinIO Art. 19: over CHF 50,000 gross earnings, over 20 contractual partners, or over CHF 5 million under unlimited power of disposal)
- Licensed manager: Swiss domicile and effective management, at least two qualified managers as a rule, irreproachable business conduct, minimum capital CHF 100,000, adequate organisation, risk management and compliance
- Supervision by a FINMA-authorised supervisory organisation, annual regulatory audit and professional indemnity cover or additional capital as required
- Manager of collective assets licence once fund assets exceed FinIA Art. 24 thresholds (generally CHF 100 million, or CHF 500 million for unleveraged portfolios with a five-year lock-in)
- FinSA: conduct rules and client adviser registration where the office provides financial services to clients outside the family
- AMLA: analyse financial intermediary status; if caught and not FINMA-supervised, join a recognised SRO and implement KYC, beneficial owner identification and reporting
- Legal Entities Transparency Act: report beneficial owners of each Swiss entity to the federal Transparency Register within the applicable deadline
- Company law: AG with CHF 100,000 share capital (at least CHF 50,000 paid in) or GmbH with CHF 20,000, at least one Swiss-resident authorised signatory, entry in the Zurich commercial register
- Tax: arm's-length remuneration of services to family members and entities (often confirmed by advance ruling), VAT registration where taxable turnover exceeds CHF 100,000, CRS/FATCA classification of every entity
Structure designs
Stand-alone SFO company in Zurich
CHF 100,000 AG share capital (GmbH CHF 20,000)
A Zurich AG or GmbH employing the family's CIO, analysts, accounting and administration staff and serving only persons with family ties. Suits families that want close contact with banks and managers and full control without a FINMA licence; usually remunerated on a cost-plus basis agreed with the tax office.
Holding AG with an embedded office
A Swiss holding company owning the operating business, direct investments and real estate, with the family office as a division or subsidiary. Participation relief largely removes tax on qualifying dividends and gains; suits entrepreneurial families whose wealth is still tied to a company.
Trust, PTC or Liechtenstein foundation above the Zurich office
A discretionary trust administered by a private trust company, or a Liechtenstein foundation, owns the wealth and the Zurich office provides investment and administrative services to it. The family-tie rules extend to offices controlled by family trusts and foundations, supporting continuity across generations.
Family fund (L-QIF or foreign fund)
A Swiss limited qualified investor fund — available since 1 March 2024 without FINMA product approval but managed by a FINMA-licensed institution — or a Luxembourg RAIF/SCSp, to pool investments of several family branches with unitised ownership and institutional reporting.
FINMA-licensed multi-family office
CHF 100,000 minimum capital
A portfolio manager licensed under FinIA and supervised by a supervisory organisation, able to admit unrelated families and share costs. Suits families who want to professionalise the office, retain talent with a commercial platform or open it to friends and co-investors.
Split model: office in Zurich, residence elsewhere
The operating office sits in Zurich for access to the banking ecosystem, while principals live in a canton such as Zug, Schwyz or Geneva that still offers lump-sum taxation or lower personal taxes. Requires careful handling of the place of effective management and of each principal's role.
Step-by-step process
- 1
Perimeter analysis
Map every person and entity the office will serve against FinIO Art. 4, test FinIO Art. 19 commerciality, and assess FinSA and AMLA status.
- 2
Tax and residence modelling
Compare Zurich ordinary taxation with other cantons for the principals, model company, capital and wealth taxes, and decide where the family will live.
- 3
Structure and governance design
Choose the office company, holding, trust, PTC or foundation and fund layers, define the investment committee and draft a family charter.
- 4
Advance tax ruling
Agree the office's cost-plus remuneration and the treatment of holding income with the Cantonal Tax Office Zurich where certainty is needed.
- 5
Incorporation and registers
Notarise the articles, pay in capital, register with the Zurich commercial register and file beneficial owner data with the Transparency Register.
- 6
Banking, office and people
Open custody and operating accounts, lease premises, appoint the board and recruit staff, applying for permits for non-EU/EFTA hires within federal quotas.
- 7
Licensing and ongoing compliance
For an MFO, affiliate with a supervisory organisation and file with FINMA; otherwise join an SRO if AMLA applies, and maintain accounts, audits, tax returns and CRS/FATCA reporting.
Typical documents
- Certified passports and proof of address for family members, directors and officers
- Family tree documenting the family ties of every person to be served
- Source-of-wealth and source-of-funds evidence (sale agreements, dividend history, audited accounts, tax returns)
- Ownership and control chart including any trust, foundation or private trust company
- Notarised articles of association, founding deed, Swiss capital deposit confirmation
- Commercial register application and Transparency Register beneficial owner filing
- Service agreements between the office and family entities, with cost-plus pricing documentation
- Investment policy, family charter and investment committee terms of reference
- For an MFO: FINMA licence application, organisational rules, business plan, CVs, criminal record and debt enforcement extracts of managers
- Residence and work permit applications for relocating principals and staff
How Legal Wealth helps

Legal Wealth helps families decide whether a Zurich office should be a single family office, a licensed multi-family office or part of a wider Swiss–Liechtenstein structure. We map family ties against the FinIA exemption, coordinate with licensed Swiss lawyers and tax advisers on rulings, AMLA and FinSA analysis, prepare source-of-wealth files, organise incorporation, banking and Transparency Register filings, and support residence planning across cantons and family governance documents. Our work is compliance-first and discreet, and every structure is built around the family's long-term legacy; enquiries are welcome at info@legalwealthglobal.com.
Enquire with Legal WealthFrequently asked questions
Does a single family office in Zurich need a FINMA licence?
No, provided it manages solely assets of persons with family or business ties as defined in FinIA Art. 2(2)(a) and FinIO Art. 4. Managing assets for unrelated families on a commercial basis generally requires a portfolio manager licence.
Can I use lump-sum taxation if I live in Zurich?
No. Canton Zurich abolished lump-sum taxation with effect from 1 January 2010. Families who want it usually reside in a canton that still offers it, such as Zug, Schwyz or Geneva, and run the office in Zurich. The federal minimum tax base for lump-sum taxpayers is CHF 435,000 for 2026.
What does a Zurich family office company pay in tax?
Ordinary profit tax of roughly 19.5–19.6% combined in the city of Zurich, plus cantonal capital tax. Qualifying dividends and gains on participations benefit from participation relief, and fees charged to family entities must be at arm's length.
Does AMLA apply to a single family office?
It may. An office with powers of disposal over the assets of others can be a financial intermediary, and AML exemptions for family relationships are narrower than the FinIA exemption. Each case needs analysis and, where caught, SRO membership.
Can a Swiss family office set up its own fund?
Yes. Since 1 March 2024 the Swiss limited qualified investor fund (L-QIF) can be launched without FINMA product approval, but it must be managed by a FINMA-licensed institution. Many families use foreign funds such as a Luxembourg RAIF instead.
What changes in 2026?
The Legal Entities Transparency Act took effect on 1 October 2026, introducing a federal beneficial ownership register with transitional deadlines for existing companies. The federal inheritance tax initiative was rejected on 30 November 2025, so cantonal rules continue to apply.
Last reviewed: 2026-10. Requirements, fees and timelines change. Information is general, reviewed on the date shown, and is not legal or tax advice.
Sources
- FinIA Article 2 (scope and exceptions)
- FinIO Article 4 (family ties)
- FINMA: Portfolio managers and trustees
- Canton Solothurn tax newsletter 01/2025: federal lump-sum minimum CHF 434,700
- La Télé: Zurich voters reject corporate profit tax cut (18 May 2025)
- Lenz & Staehelin: Legal Entities Transparency Act in force 1 October 2026